Air Conditioning and Home Insurance: What You Need to Tell Your Insurer
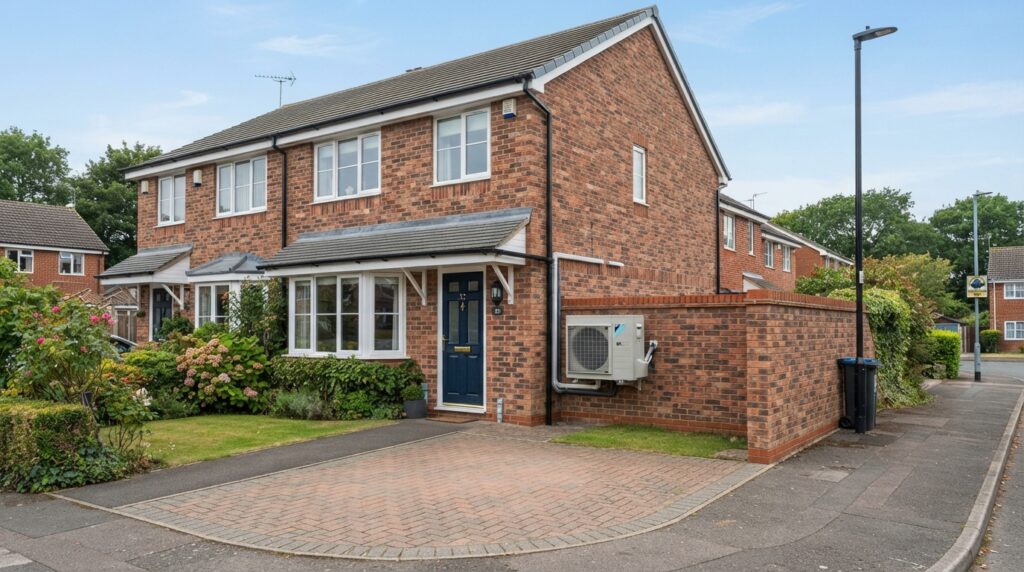
A portable unit: generally nothing to declare — it’s an appliance, like a fridge. Check it’s covered under contents if it’s valuable. A fixed split system: this is a material alteration to the building, and you should tell your insurer. The bigger risk isn’t the premium, it’s a declined claim — for water damage from a badly installed system, or because you didn’t disclose something the insurer considers material. Keep the F-Gas and electrical certificates; they’re the evidence that matters.
Nobody enjoys reading insurance documents, but this one is worth ten minutes — because the failure mode isn’t a slightly higher premium, it’s discovering at claim time that you’re not covered.
Portable units: simple
A portable air conditioner is a household appliance. You plug it in, and nothing about the building changes.
- Nothing to declare in the ordinary course. You don’t tell your insurer about a new kettle, and this is the same category.
- Covered under contents, like other appliances, subject to your policy’s terms and any single-item limit. If yours cost several hundred pounds, check it’s within that limit.
- Damage it causes may be covered under accidental damage if you have that cover — a leaking unit damaging a carpet, for instance. Accidental damage is frequently an optional add-on rather than standard, so check.
- It goes with you when you move, and remains contents.
This simplicity is a genuine and underrated advantage of portables, alongside no planning permission, no certification requirement and no EPC implication. Our portable vs split guide covers the wider comparison.
Fixed systems: tell your insurer
A split system is a permanent alteration involving an outdoor unit, pipework through the building fabric, and usually a new electrical circuit.
Home insurance policies generally require you to notify the insurer of material changes to the property, and structural or installation work commonly falls within that. Whether a particular insurer treats domestic air conditioning as material varies — which is exactly why you ask rather than assume.
A short call or message, and a note of the response, costs nothing. Non-disclosure is what causes problems.
The certification point, which matters most
This is the part people most often get wrong, and it’s where a claim genuinely can fail.
Work on the refrigerant circuit requires F-Gas certification, and installing a new electrical circuit is notifiable under Part P of the Building Regulations in England and Wales. Our installation law guide covers both in detail.
If a system installed without proper certification later causes damage — water ingress from condensate, an electrical fault, a fire — an insurer is entitled to ask how it was installed. Policies commonly exclude damage arising from faulty workmanship or from work not carried out to required standards.
What to keep, and where:
- The electrical installation certificate or minor works certificate
- Building control notification or self-certification paperwork
- The installer’s F-Gas company certification details
- The invoice and any warranty documentation
- Any planning permission or confirmation it wasn’t required
Keep digital copies. You’ll want these for a claim and again when you sell — conveyancing enquiries ask about building work.
What’s typically covered, and what isn’t
Generalisations, and your policy governs — but the usual pattern:
Often covered:
- Storm damage to an external unit, subject to the policy’s definition of storm
- Theft of an outdoor unit, which does happen
- Escape of water damage from a genuine sudden failure
- Fire or lightning damage
- Accidental damage, if you have that cover
Typically not covered:
- Mechanical or electrical breakdown of the unit itself — that’s what a warranty or service contract is for, not buildings insurance
- Wear and tear, and gradual deterioration
- Gradual leaks that developed slowly rather than suddenly — a very common decline reason
- Damage from poor installation or faulty workmanship
- Damage from lack of maintenance
- Frost damage in some policies, which is worth checking for an outdoor unit
The outdoor unit and your neighbours
Two liability points worth knowing.
Damage to a neighbour’s property. If your outdoor unit came loose in a storm and damaged next door, the question is generally whether you took reasonable care — a well-maintained, properly mounted unit failing in exceptional wind is treated differently from one that was visibly insecure. Public liability cover within your home insurance may respond. Our storm-proofing guide covers securing things properly, which matters given this winter’s storm-leaning outlook.
Noise disputes. Not an insurance matter directly, but relevant: conveyancing forms ask about disputes with neighbours, including complaints made or received. A running dispute over a noisy unit can complicate a sale. Our noise guide covers resolving these.
If you’re a landlord
Landlord insurance differs from owner-occupier policies, and there are extra considerations.
- Tell your insurer about any fixed installation.
- Portable units you provide become your responsibility as landlord’s contents, and need to be safe and maintained.
- Electrical safety obligations apply to installations in rented property, with periodic inspection requirements in England.
- The EPC angle matters more for landlords, given minimum energy efficiency standards for letting — our EPC and value guide covers why fixed comfort cooling can count against a rating.
Our landlords guide covers the wider picture.
If you’re a tenant
Your contents insurance covers your belongings, including a portable unit you own. The building is your landlord’s responsibility.
Don’t install anything fixed without written permission — that’s an alteration to someone else’s property, and it can affect both their insurance and your deposit. Our renter setup guide covers doing it without permanent changes.
A short practical checklist
- Portable unit? Check it’s within your contents single-item limit. That’s usually it.
- Fixed system? Call your insurer before installation, not after, and note what they say.
- Use certified installers and collect all paperwork.
- Read your policy’s exclusions — specifically gradual damage, faulty workmanship and maintenance requirements.
- Service it annually and keep the records. This is your evidence against a “lack of maintenance” decline.
- Photograph the installation when it’s done, including the outdoor unit’s mounting.
Frequently asked questions
Will a fixed system increase my premium?
Possibly modestly, possibly not at all — insurers vary. The premium is much less of a concern than a declined claim, which is why disclosure matters more than the cost of disclosing.
Do I need to declare a portable unit?
Generally no — it’s an appliance. The only thing worth checking is whether its value sits within your contents policy’s single-item limit.
What if the previous owner installed one and I’ve no paperwork?
Worth flagging to your insurer, and worth trying to trace the installer. In practice, missing paperwork for existing installations is common — an indemnity policy is sometimes used at the point of sale. Take your conveyancer’s advice.
Is the unit itself covered if it breaks down?
Not usually under buildings or contents insurance — mechanical and electrical breakdown is generally excluded. That’s what the manufacturer’s warranty or a separate service contract covers. Our extended warranties guide covers whether those are worth buying.
My claim was declined. What now?
Ask for the decline reason in writing and check it against your policy wording. If you still disagree, complain to the insurer formally, and if unresolved after eight weeks or on receiving a final response, the Financial Ombudsman Service can consider it — free to you.
Sources
- Financial Ombudsman Service — Buildings insurance complaints (common dispute causes, including gradual damage)
- Financial Ombudsman Service — How to complain
- Association of British Insurers — Home insurance guidance
- GOV.UK — Fluorinated gases (F-gases): rules
- GOV.UK — Approved Document P: Electrical safety
- GOV.UK — Electrical safety standards in the private rented sector
- Citizens Advice — If your insurance claim is rejected
Related reading: our installation law guide and value and EPC guide.
Related guides
Compare current prices, stock and reviews on portable air conditioners at Amazon UK. Prices and stock move fast in a heatwave, so it is worth checking before you commit.
Browse air conditioners →